Short answer: in Quebec, your windshield is covered only if your policy includes coverage for damage to your own vehicle, known as Chapter B, which is optional. If it does, a deductible may apply, and it can differ for a repair and for a replacement. Only your insurer can confirm your coverage and your deductible: call before the work is done. This guide explains how it generally works, based on official sources, so you know what to ask.
General information, not personalized advice: every policy is different. Liqui Pneus is neither an insurer nor an insurance representative. The official sources cited are in French.
The two parts of car insurance in Quebec
The Autorité des marchés financiers (AMF), Quebec's financial regulator, and the Insurance Bureau of Canada (IBC) describe the same split:
- Chapter A, civil liability: mandatory. It protects you when your vehicle causes damage to others. It does not pay for damage to your own vehicle, so it does not pay for your windshield.
- Chapter B, damage to your vehicle: optional. The law does not require it, but if you financed your vehicle or lease it long term, your contract will probably require this coverage, the AMF notes. This is the chapter that can cover a windshield.
Which coverage pays for a broken windshield?
Chapter B includes several types of coverage. Quebec's standard owner's policy form approved by the AMF, Q.P.F. No. 1, lists four:
- "all perils" coverage;
- coverage against collision and upset;
- coverage against perils other than collision or upset, often called "comprehensive";
- coverage against specified perils, such as fire, hail or theft.
The form states that coverage against perils other than collision or upset includes, among other things, falling or flying objects and projectiles: the typical case of a stone thrown up on the highway. "All perils" coverage covers every type of peril, except the policy's exclusions.
Watch for endorsements. The AMF publishes an endorsement form that restricts Protection 3 for the vehicle's windows (Q.E.F. No. 13c). If such an endorsement appears in your policy's particular conditions, your glass coverage is different. Reread your policy or ask your insurer.
The deductible: what you pay yourself
The deductible is the amount the insurer does not pay: the indemnity equals the value of the damage, minus the deductible. It is set for each type of coverage, in the policy's particular conditions or in its endorsements. The higher the deductible, the lower the premium, the AMF reminds us.
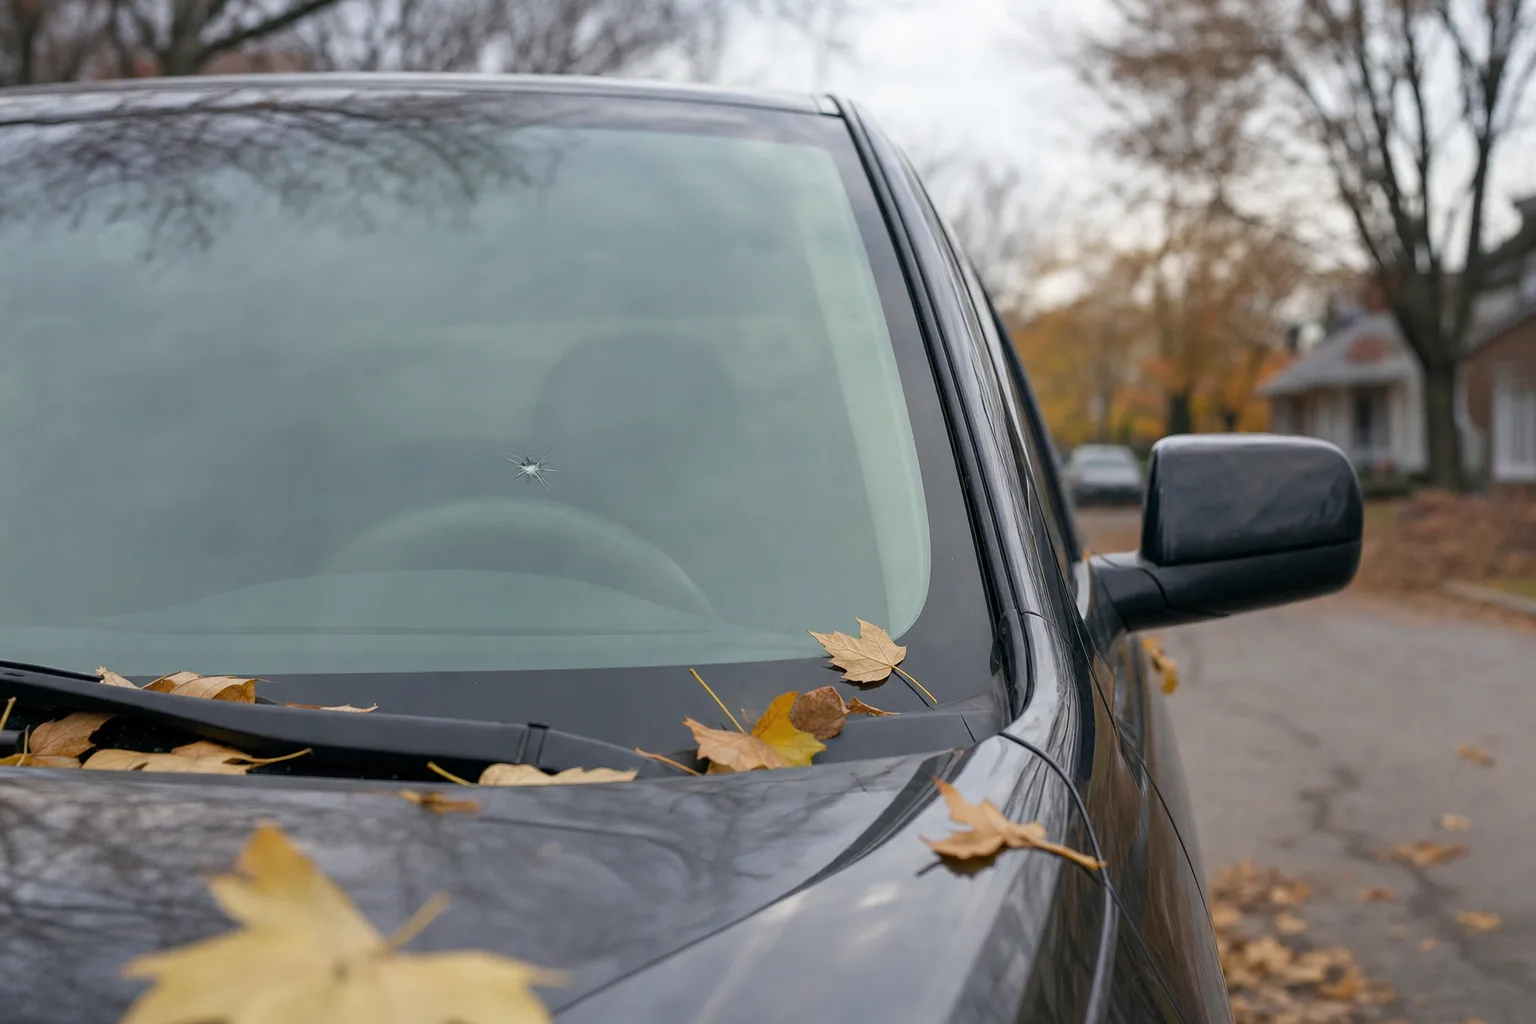
For windshields, CAA-Québec says that with "all perils" or "comprehensive" coverage, there is generally no deductible for a repair, while a deductible is generally charged for a replacement. That is a trend, not a rule: only your policy is binding. It is also a good reason to have a small chip repaired before it becomes a crack, because at Liqui Pneus, a crack is not repaired: it requires a replacement, on quote.
Will a claim raise my premium?
There is no single answer. The AMF explains that premiums depend on several criteria, including your driving record and your accidents, whether or not you were at fault. According to CAA-Québec, a windshield repair generally has no effect on your premium or your insurance record, while a replacement could affect your premium at renewal. Ask your insurer before you claim: only they can answer for your policy.
Filing a windshield claim, step by step
- Write down the facts: the date, the place and the cause of the damage (a stone, a falling object, a crack that grew), and take photos.
- Report the loss promptly. The Civil Code of Québec requires the insured to notify the insurer of any loss that may give rise to an indemnity as soon as they become aware of it (article 2470).
- Wait for the go-ahead before the work. The standard policy form provides that no repairs should be made until the insurer has examined the vehicle within a reasonable time, unless needed to protect the vehicle or with the insurer's written consent. Ask your insurer how it handles windshields.
- Get a price. For a replacement, request a quote with your VIN: the price depends on the glass features, such as a driver assistance camera, a rain sensor, a heated area or a head-up display.
- Keep the detailed invoice for the work: it is the supporting document for your claim.
- Be accurate. A false statement forfeits the right to an indemnity for the peril concerned (Civil Code, article 2472).
The insurer must then pay the indemnity within 60 days of receiving the notice of loss or, if it asked for them, the relevant information and supporting documents (Civil Code, article 2473).
Questions to ask your insurer
- Does my policy include Chapter B coverage for glass?
- Is there an endorsement that restricts my glass coverage?
- What deductible applies to a chip repair? To a replacement?
- Do you need to examine the vehicle or approve a price before the work?
- Can I choose the shop that does the work?
- Will this claim affect my premium at renewal?
- Which documents do you want: detailed invoice, photos, VIN?
How Liqui Pneus helps
At our Laval shop, we repair windshield chips and replace windshields, by appointment Monday to Friday. We do not quote any deductible or reimbursement amount: only your insurer can confirm them. We give you a detailed invoice for the work, to send with your claim. For a replacement, the quote prepared with your VIN gives you a precise price to show your insurer.
To find out whether your damage can be repaired, read Repair or replace a windshield: how to decide. And if you are wondering whether you can drive in the meantime, see what the law says in Quebec.
Laval shop
Windshield in Laval
Fixed-price chip repair and windshield replacement on quote with your VIN, at our shop, 1870 Cunard Street, Monday to Friday.
FAQ
Frequently asked questions
Does my car insurance cover my windshield?
Only if your policy includes coverage for damage to your vehicle (Chapter B), which is optional in Quebec, and depending on its endorsements. Check with your insurer.
Is there a deductible for a windshield?
Often for a replacement. According to CAA-Québec, there is generally none for a repair with "all perils" or "comprehensive" coverage. Your policy sets the deductible for each type of coverage.
Should I call my insurer before the repair?
Yes. The Civil Code requires you to report the loss as soon as you become aware of it (art. 2470), and the standard policy form provides that no repairs are made before the insurer's examination, unless needed to protect the vehicle or with its written consent.
Can Liqui Pneus tell me what my insurance will pay?
No. Only your insurer can confirm your coverage, your deductible and the amount reimbursed. We give you a detailed invoice for the work for your claim.
How long does the insurer have to pay?
The Civil Code (art. 2473) requires it to pay the indemnity within 60 days of receiving the notice of loss or, if it asked for them, the relevant information and supporting documents.